Regime 42: when Northern Ireland onward supply relief applies
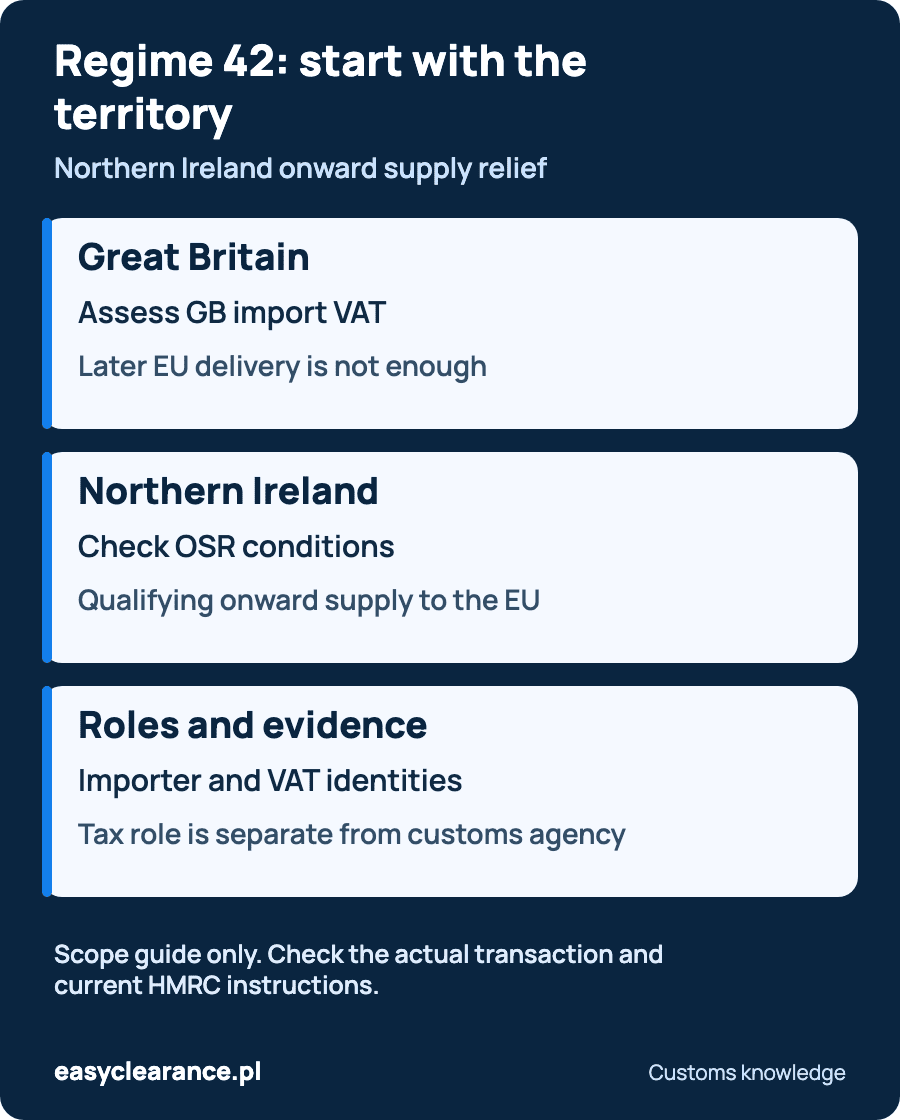
Start with the place of import, not a promised VAT saving. HMRC's current instructions for procedure 4200 cover specified imports into Northern Ireland followed by a qualifying onward supply to an EU Member State. They do not describe a general VAT-free import procedure for goods arriving in Great Britain.
This is a general procedural guide. It does not describe a verified customer shipment or promise a particular financial result.
Where procedure 4200 fits
The 4200 section of HMRC's current CDS instructions lists movements from Great Britain to Northern Ireland and from the rest of the world to Northern Ireland. It concerns release for free circulation with a qualifying onward supply to another EU Member State. Other requested or previous procedures have their own completion instructions; do not select a code from a headline alone.
For an ordinary import into Great Britain, establish the correct GB customs and VAT treatment separately. An eventual export to an EU country does not, by itself, turn the GB import into Northern Ireland onward supply relief. The place of import and the actual supply chain matter.
Relief from import VAT is not relief from every charge
HMRC describes onward supply relief as an import VAT relief subject to conditions. Applicable customs duties still have to be paid or accounted for. The onward transaction and VAT accounting in the destination Member State also need to be addressed.
Check that the planned goods, onward supply and parties meet the relevant conditions. Do not assume that a customer address in the EU, an EORI number or a later transport document is sufficient on its own.
Identify the importer and the right kind of representative
HMRC's claim instructions require the relevant XI VAT identification, the purchaser's EU VAT identification, onward transport particulars, an appropriate procedure and commodity code, XI EORI and access to CDS. The detailed party instructions distinguish the importer, destination customer and tax representative roles.
Customs representation and VAT tax representation are separate matters. A customs agent acting as a direct representative is not automatically the tax representative for onward supply relief. Confirm the actual appointment, establishment and VAT responsibilities rather than treating a customs mandate as evidence of both roles.
This guide makes no claim that Easy Clearance holds a particular tax-representation appointment or simplified-procedure authorisation. The appropriate parties and their responsibilities must be established for the actual movement.
Build the evidence before the declaration
Before claiming, confirm the onward-dispatch deadline and any extension requirements that apply to the specific procedure. Do not assume an extension will be granted or that different timing expressions have the same starting point.
- Record where the goods enter and which jurisdiction's import rules apply.
- Identify the importer, seller, EU purchaser or relevant own-transfer party and any properly appointed tax representative.
- Check the goods description, commodity code, customs value and applicable duties.
- Retain the contract and planned onward-transport details needed for the relief.
- Agree who will maintain the onward-supply evidence and complete the relevant VAT return and EC Sales List reporting.
An illustrative route, not a client case
Consider goods imported from outside the EU into Northern Ireland, with a documented onward supply to an EU customer. The practical question is whether that movement and those parties satisfy the relief conditions, including the evidence and reporting requirements. No shipment value, approval timescale or saving is assumed here.
For goods entering Great Britain and subsequently leaving for the EU, review the GB import, any transit or other customs procedure, the export and the destination import separately. Do not transfer an example from one territory to another without checking the actual facts.
Compare the appropriate VAT treatment
Postponed VAT accounting may be relevant for an eligible VAT-registered importer, but it is a way of accounting for import VAT, not a universal tax exemption. Compare the treatment that is actually available for the territory and transaction. A fixed cash-freeze period, guaranteed refund or standard return on investment cannot be inferred from the procedure name.
Frequently asked questions
Can I use procedure 4200 for an ordinary Dover import?
HMRC's current 4200 instructions specify imports into Northern Ireland from Great Britain or the rest of the world, with a qualifying onward supply to an EU Member State. They do not establish a general VAT-free route for ordinary imports into Great Britain through Dover.
Does a GB EORI or a direct customs representative establish eligibility?
No. The territory, transaction, importer and VAT identification requirements must be checked. Customs representation is separate from the tax representative role used for onward supply relief; a customs mandate does not establish the tax appointment.
Does onward supply relief remove customs duty?
Not automatically. HMRC's 4200 instructions require applicable customs duties to be paid or accounted for. Import VAT relief and customs duty treatment must be assessed separately.
Does this guide report an actual customer saving?
No. It explains the procedure's scope and the checks needed for a proposed movement. It does not assert a completed customer shipment, authorisation, financial saving or refund timescale.
Official sources and guidance
Sources checked for this revision on 17 October 2026. HMRC completion instructions and guidance are distinguished from legislation; check the current instructions for the specific movement.
- HMRC: requested procedure 4200
- VAT Directive, Article 143 (official UK mirror)
- Withdrawal Agreement: Northern Ireland VAT framework
- HMRC: check onward supply relief eligibility
- HMRC: claim onward supply relief
- HMRC: CDS parties and representation
- Customs representation: UCC Article 18 (official UK mirror)
- HMRC: postponed VAT accounting
Discuss the actual movement
Send the route, goods description and intended customs treatment so the relevant document checks can be identified.
WhatsApp: +44 7404 091503Contact Easy Clearance