Regime 42 and import VAT: compare the right route and cashflow
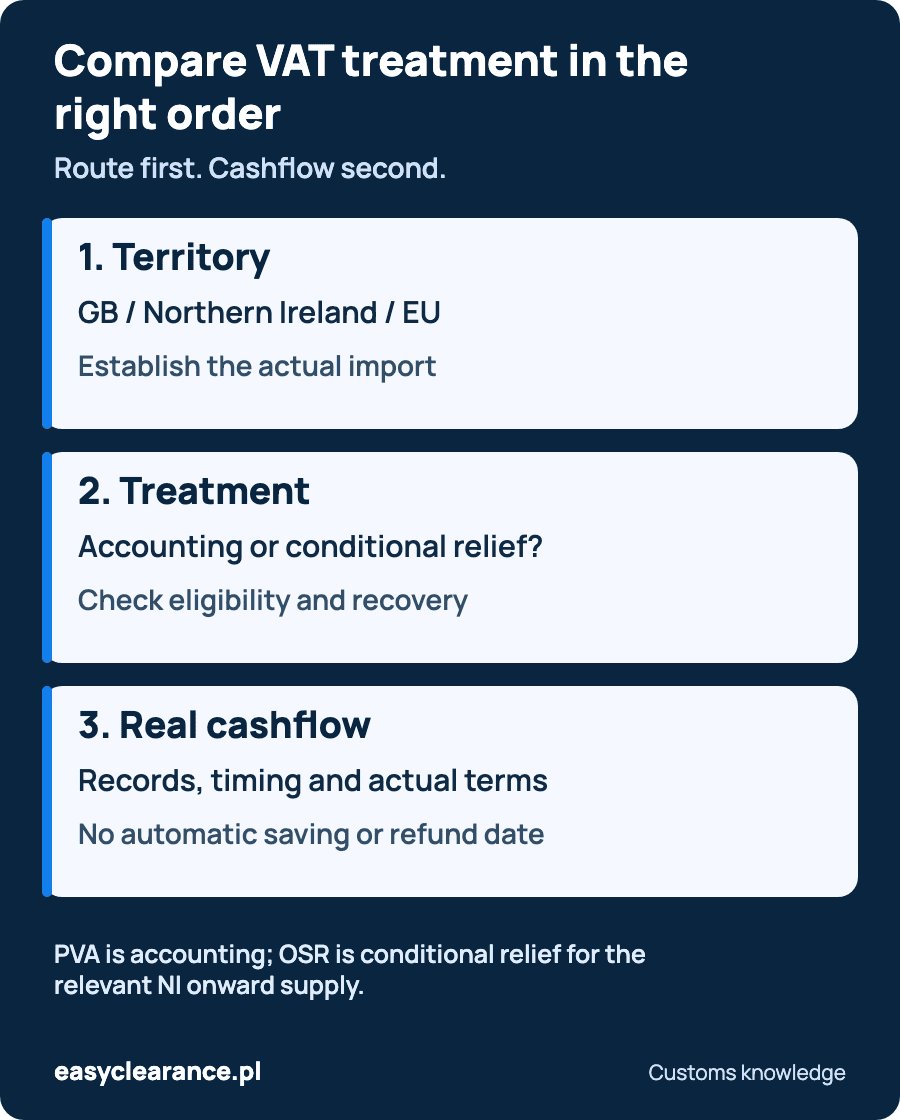
A useful comparison starts with the customs territory and the transaction. Northern Ireland onward supply relief and postponed VAT accounting address different questions. Neither should be presented as an automatic financial upgrade for every UK import.
Begin with the territory and destination
For goods entering Great Britain, assess the GB import and any later export or destination-country import on their own facts. A plan to send the goods to Poland or another EU country does not, on its own, establish eligibility for procedure 4200.
For a Northern Ireland import followed by a qualifying supply to an EU Member State, onward supply relief may be relevant if its conditions are met. HMRC's 4200 instructions specify permitted movements, the intended onward supply and the required declaration information. Applicable customs duties are still a separate consideration.
What postponed VAT accounting changes
HMRC describes postponed VAT accounting as accounting for import VAT on the VAT return rather than paying it at import, where the importer and movement qualify. Deductible input VAT can be recovered on the same return subject to the normal rules. Accounting for VAT and being entitled to deduct it are not the same question.
This means a comparison must not assume that every standard import requires an upfront cash payment followed by a refund. Check the importer's VAT status, entitlement to recovery, instructions to its customs representative and the records needed for the return. The appropriate method depends on the actual circumstances.
What onward supply relief changes
Onward supply relief is a conditional import VAT relief for the relevant Northern Ireland onward-supply situation. It does not remove the need to meet the transaction, identity, transport, reporting and evidence requirements. It does not make all customs duties disappear.
Confirm the importer and any tax representative, the relevant XI and EU VAT identities, the onward movement and who will retain the evidence. Check the applicable dispatch deadline in the current instructions rather than assuming that every timing formulation is identical.
A practical comparison checklist
These are planning questions, not a fixed break-even formula. Obtain the actual facts and terms before modelling a financial result.
| Question | What to establish |
|---|---|
| Where is the import? | Great Britain, Northern Ireland or an EU Member State; do not mix their procedures. |
| What is the next transaction? | Domestic sale, qualifying onward supply, export, transit or another procedure. |
| Who accounts for VAT? | The actual importer and any valid tax-representative arrangement. |
| Can input VAT be deducted? | The business's recovery entitlement and supporting evidence. |
| What cash is actually paid? | The available accounting method, payment timing and commercial terms. |
| What work and risk remain? | Declarations, guarantees where relevant, transport proof and VAT reporting. |
Keep representation and business costs separate
A customs representative's mandate does not automatically appoint a VAT tax representative. Confirm each role and responsibility explicitly. Do not assume that an agent's own authorisation or VAT status can simply be borrowed by an importer.
Commercial handling costs, any separately agreed security, accounting work and potential VAT recovery restrictions may affect the decision. This guide publishes no agency price, standard refund period, guaranteed saving or promised implementation time.
What to send for an initial review
With these facts, the available procedures can be compared before costs are discussed. A route-based recommendation is more useful than selecting a procedure because its name appears to promise zero VAT.
- The real route, points of entry and destination, and intended customs treatment.
- The importer, seller and purchaser identities and relevant VAT/EORI registrations.
- The goods description and intended use, with the commercial documents.
- The proposed onward supply or other transaction and available transport evidence.
- The VAT-accounting method currently used and any limits on deduction.
Frequently asked questions
Is Regime 42 always better than standard import VAT accounting?
No. First establish the territory, transaction and eligibility. Northern Ireland onward supply relief is conditional, while the importer's available VAT-accounting method and recovery entitlement determine the actual cashflow comparison.
Does PVA mean import VAT is exempt?
No. PVA changes how qualifying import VAT is accounted for. HMRC describes declaring import VAT and recovering deductible input VAT through the VAT return, subject to the normal rules. Deductibility must be checked separately.
Can a standard refund period or break-even shipment value be promised?
Not from the procedure name alone. The result depends on the actual movement, available VAT accounting, deduction entitlement, records and commercial terms. This guide does not give a universal refund deadline or guaranteed financial result.
Does appointing a customs agent settle the tax-representative requirements?
Not automatically. Customs representation and the tax representative role have different responsibilities. Check the appointment and the applicable VAT and customs requirements for the actual supply chain.
Official sources and guidance
Sources checked for this revision on 17 October 2026. HMRC completion instructions and guidance are distinguished from legislation; check the current instructions for the specific movement.
Discuss the actual movement
Send the route, goods description and intended customs treatment so the relevant document checks can be identified.
WhatsApp: +44 7404 091503Contact Easy Clearance