Returned Goods Relief (RGR): How to Re-Import Goods Without Paying Duty Again
Returned Goods Relief (RGR) lets you bring back goods you previously exported without paying import duty again, and without import VAT where the same person exported and re-imports. The goods must return unaltered within three years, and you must prove the original export. In UK CDS you claim it with procedure code 6110 plus F01 or F05.
Status
verified against official sources
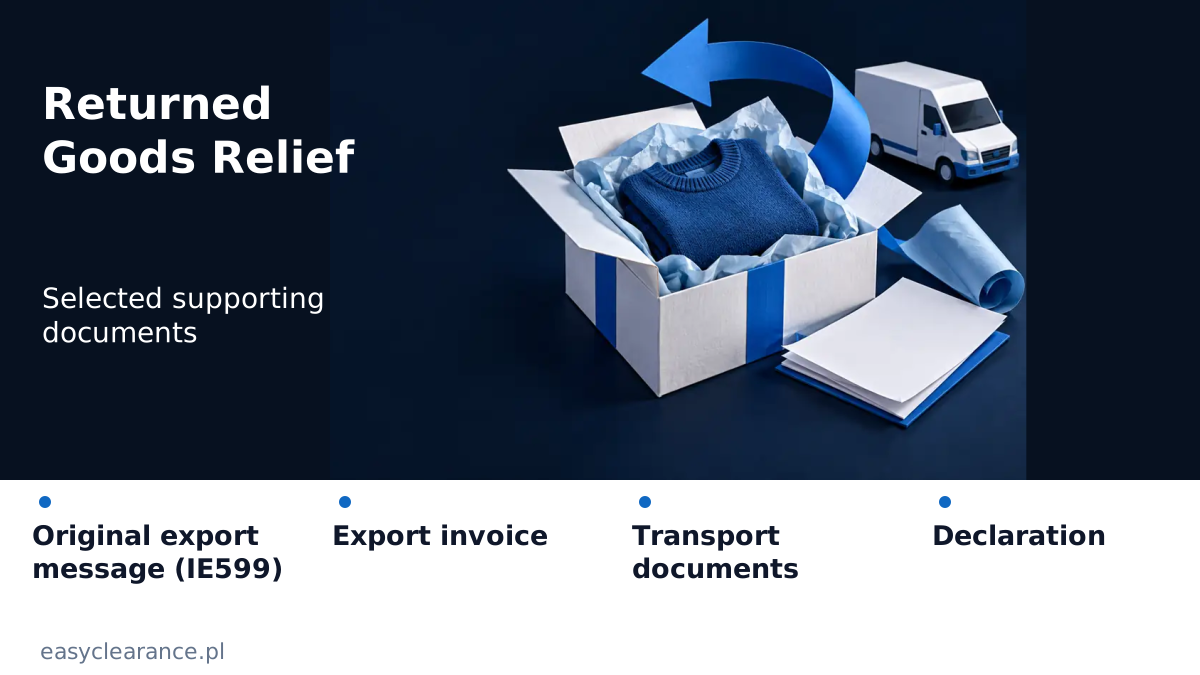
Checklist before you claim
Goods exported in free circulation, back within three years, unaltered, with the export MRN to hand. Declare in CDS under 6110 with F01 (duty) or F05 (duty and VAT).
Returned Goods Relief is the customs relief that stops you paying import duty and VAT twice on your own goods. It matters whenever a customer rejects a parcel, a trade-show shipment comes back, or hired equipment returns home. This guide explains how the relief works, who can claim it, how to declare it in the UK Customs Declaration Service (CDS), and how it differs in the EU.
Need operational support?
Send a quick brief and get a clear next-step plan.
What is returned goods relief (RGR)?
RGR is a relief from import duty, and in many cases import VAT, for goods that were exported and then come back. The idea is simple: duty is meant to apply to goods entering a customs territory for the first time, not to your own goods making a round trip.
In the UK, HMRC's guidance on re-importing goods describes the relief and its conditions. HMRC's CDS notes for procedure code 6110 cite Article 203 of the Union Customs Code alongside the UK Customs Tariff reliefs and the Taxation (Cross-border Trade) Act 2018. In the EU, the same Article 203 is the legal basis. It gives relief to non-Union goods that were originally exported as Union goods and return to the EU customs territory within three years.
Searches for "return goods relief", "returned good relief" or "RGR customs" all point to the same relief. The conditions concern the goods' export history and customs status, not the nationality of the product.
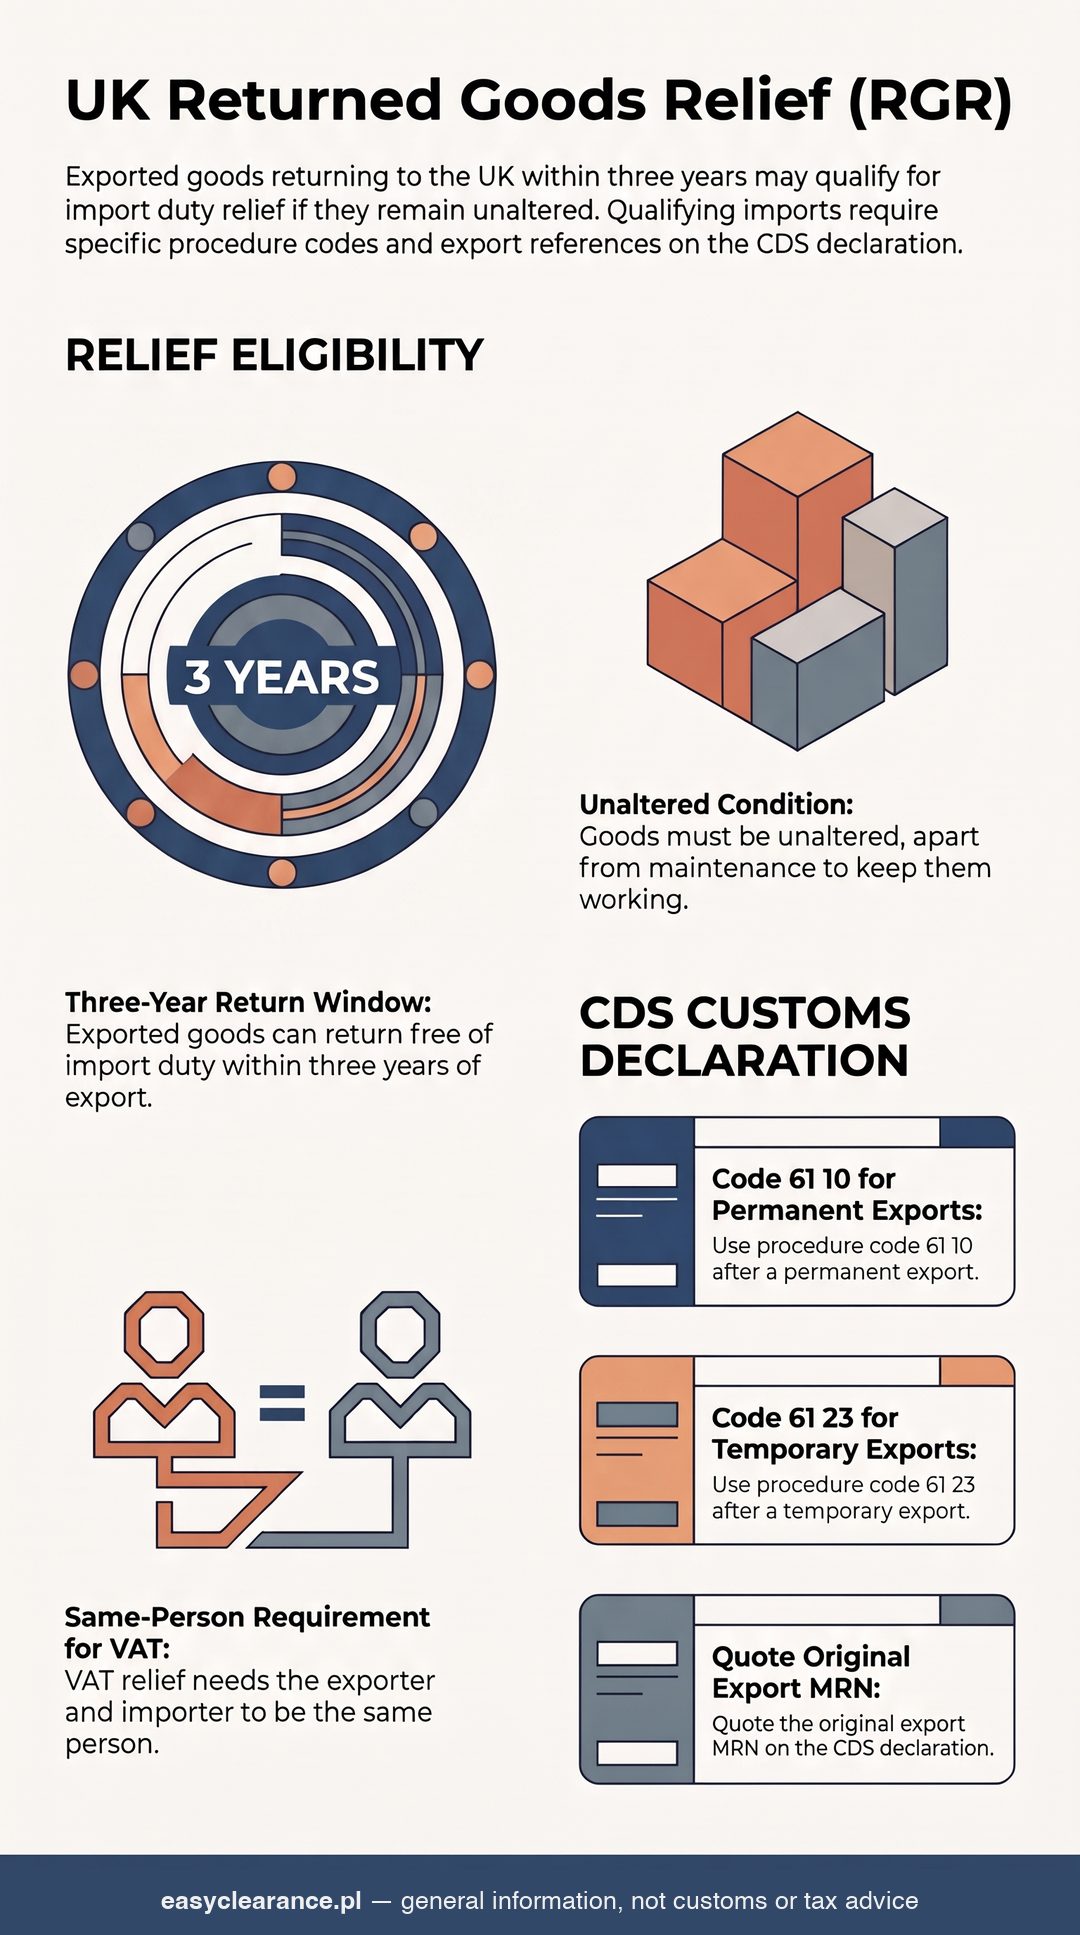
Who can claim returned goods relief and on what conditions?
HMRC sets out these conditions for UK re-imports:
- Previously exported: the goods were exported from the UK. Certain Northern Ireland movements are also covered, and some Northern Ireland exports are excluded.
- Free circulation at export: the goods were in free circulation when they left, unless they were under inward processing or end-use.
- Unaltered: the goods return in an unaltered state, apart from maintenance. They must not have been upgraded to increase their value.
- Not exported for repair or processing: if the work was not carried out, relief may still apply.
- Within three years: partial returns qualify.
- Same person for VAT: for VAT relief, the exporter and importer must be the same person.
- Refunds repaid: HMRC's CDS notes say customs duties or other charges refunded at export must be repaid before the goods are released, and that any revenue reclaimed at export (for example VAT zero-rated for export) must be repaid on import.
Goods that were sold while abroad lose VAT relief unless the specific conditions in HMRC guidance are met. Check the commodity code too: if the goods are strictly controlled, an import licence may still be needed.
How long do you have to return the goods?
The standard time limit is three years from export, in both UK and EU rules. HMRC allows six years for Crown servants returning from overseas postings. Shorter periods apply to goods that benefited from agricultural measures, and those must be declared for free circulation within 12 months of completing export formalities.
The three-year limit can be waived in listed situations, including specialised equipment on long-term hire or loan abroad, building equipment used in capital projects abroad, exhibition goods on long-term display, and goods delayed by circumstances beyond your control. You apply to the National Import Reliefs Unit, explaining the circumstances. Article 203(2) of the Union Customs Code similarly allows the period to be exceeded for special circumstances in the EU.
Returned goods relief UK: how to claim it in CDS
For goods coming into Great Britain, you claim RGR in the import declaration. The steps below describe a typical freight shipment.
- Collect proof of the original export. Find the export declaration, its MRN, the export invoice and the transport documents.
- Confirm eligibility. Check the conditions above, including who the exporter and importer were, because VAT relief depends on it.
- Declare under procedure code 6110. HMRC describes 6110 as release for free circulation of re-imported goods in an unaltered state while claiming RGR.
- Add the correct additional procedure code. F01 relieves customs duty only. F05 relieves duty and VAT. Use F01 if the goods are not eligible for VAT relief.
- Quote the export MRN. Declare it as a previous document in data element 2/1 with previous document code MRN.
- Use alternative evidence only if the MRN is unavailable. Declare its reference against code ZZZ in data element 2/1.
- Pay what is not relieved. Any customs duties not covered by RGR must still be paid or accounted for.
The declarant needs a UK EORI number and access to CDS. If you do not file yourself, you can appoint a customs agent to file the declaration. HMRC expects you to give that representative clear written instructions covering the goods on which you claim relief. For an overview of the system, see our CDS guide. Easy Clearance is a customs agency registered for CDS with a UK EORI number, and the ops team can prepare the 6110 declaration for you.
Claim at the time of import. HMRC says late claims may be accepted and charges repaid if the goods are declared correctly, but it is cheaper and faster to claim up front.
Documents and proof: what is the "returned goods form"?
Most searchers asking for a "returned goods form" are looking for one document that triggers the relief. For commercial freight, the claim is made in the customs declaration, supported by your evidence. HMRC may ask you to complete forms C1314 and C&E 1158. For goods temporarily exported under a duplicate list, HMRC uses form C&E 1246.
The key evidence is the original MRN of the export declaration. If it is missing, HMRC lists acceptable alternative evidence. It must clearly identify the goods and confirm both their physical export and their duty status. Examples include:
- a copy of the export invoice, or the export airway bill or bill of lading
- a commercial certificate of shipment prepared at the time of export
- a certificate of posting for the export
- a copy of the import invoice, if it clearly shows the goods are being returned
- a statement from the manufacturer or exporter, if that is not you
- stock records, or catalogue information or a qualified opinion for collectable items
Keep the National Import Reliefs Unit's acknowledgement letters, receipts, bills, invoices and insurance documents for at least four years.
Returned goods relief EU: Article 203 and member states
When goods exported from the EU return to the EU, for example after a customer in Great Britain rejects them, Article 203 of the Union Customs Code applies. Three conditions follow from the text: the goods were exported as Union goods, they return within three years, and they come back in the state in which they were exported. The relief must be supported by information showing that the conditions are met. It can apply even if only part of the exported goods returns.
The EU rules are applied through each member state's customs authority. GOV.UK's page on EU Returned Goods Relief says the relief applies to goods re-imported into the EU that were previously exported to the UK, and it links to national guidance for individual member states. That is why searches such as "returned goods relief Ireland" lead to Irish Revenue guidance rather than to HMRC. Check the declaration codes and VAT treatment of the member state where the goods arrive.
Evidence of export on the EU side is typically the export declaration and proof that the goods left the EU. If you are missing that proof, read our guide to missing IE599 export notifications before the goods come back.
Returned goods relief UK to EU and EU to UK: which direction applies?
The direction decides which authority and rules apply:
- Exported from the UK, returning to the UK: UK RGR, declared in CDS with code 6110 and F01 or F05.
- Exported from the EU, returning to the EU: EU RGR under Article 203 UCC, declared to the member state's customs.
- EU goods that never left the EU: no RGR needed, because there was no import.
An EU-to-GB movement has extra steps beyond the relief. An entry summary declaration must be made before goods arrive in Great Britain, and HMRC's guidance records that the temporary waiver on safety and security declarations for EU goods has ended. Goods moving through locations that use the Goods Vehicle Movement Service need a goods movement reference (GMR), which must include references for the goods in the vehicle, trailer or container, such as the import MRN where the goods are declared in CDS. RGR does not replace any of these.
Special cases: repaired goods, hired equipment and Northern Ireland
Repaired or processed goods. RGR is not designed for goods sent abroad to be repaired or improved. HMRC says the goods must not have been exported for repair or processing. Declaring such goods as RGR when they have changed can lead to underpaid duty. Read our guide on returned goods relief after repair for the alternatives.
Hired, leased or loaned equipment. HMRC lists professional and commercial equipment hired, leased or loaned outside the UK among qualifying goods. Temporarily exported goods under ATA or CPD carnets can also qualify.
Pallets and reusable packaging. Pallets, containers and reusable packaging exported from the UK or EU and re-imported are on HMRC's list of eligible goods.
Inward processing and end-use. Goods that were previously under inward processing need the originally relieved duty paid on return, and HMRC says to declare them under procedure code 61 23 F01. For goods under end-use, code 1RL is used instead of F01 or F05.
Northern Ireland. HMRC covers some Northern Ireland movements: goods moved from Northern Ireland to Great Britain and returned to Northern Ireland, and EU goods moved from the EU to Great Britain and then into Northern Ireland. Rules differ depending on the status of the goods, so read our Northern Ireland and Windsor Framework guide and confirm the position before shipping.
E-commerce returns, parcels and baggage
For online sellers, the practical problem is matching each returning parcel with its original export. Our guide to e-commerce returns from the UK covers the operational side, including how to batch returns.
HMRC's rules for small-scale returns are straightforward. Personal belongings in accompanied baggage need no formal declaration if the conditions are met, while other goods such as commercial samples must be declared at the red channel or red point. For goods returned by post, the sender should write "Returned goods — relief claimed" on the package and on the customs declaration, give full descriptions, quantities and values, and quote a VAT number if registered.
VAT on goods that come back after export
VAT is where most mistakes happen. If you zero-rated the original export, HMRC expects you to deal with the return correctly. VAT Notice 703 says that if you export goods on sale or return terms, or transfer your own goods to a branch outside the UK, you must make an import declaration for any goods returned to the UK. It also says exported goods damaged after shipment and re-landed in the UK must be declared to HMRC, and that if you later sell them you must account for VAT at the appropriate UK rate on the sale price.
To keep the VAT relief, make sure the exporter named on the export declaration and the importer named on the re-import declaration are the same person. If a different entity imports, or the goods were sold abroad, plan for import VAT and check whether it can be recovered on your VAT return.
Sending back imported goods: RGR or a repayment claim?
If you are returning goods you imported, rather than re-importing your own exports, RGR does not apply. HMRC can repay or remit charges on rejected imports that do not meet the contract, are defective, or were damaged before customs clearance. The time limit is one year. If you hold an EORI number and the declaration was made in CDS, you claim in CDS. Form C&E1179 is for people with no EORI number, private individuals, and businesses that used state aid for import duty. VAT-registered businesses cannot reclaim overpaid import VAT through C&E1179 and should adjust input tax in their VAT return.
You will need the MRN, the import invoice and proof of your entitlement to the claim. HMRC aims to decide within 30 days.
Common mistakes to avoid
- Declaring goods as normal imports and discovering the relief only after duty is paid.
- Failing to quote the export MRN in data element 2/1 or to keep alternative evidence.
- Using F05 when the exporter and importer are different entities. Use F01 in that case.
- Treating repaired or upgraded goods as unchanged.
- Missing the three-year deadline without applying for a waiver first.
- Forgetting that RGR does not replace safety and security declarations or GMRs.
Frequently asked questions
What is returned goods relief?
Returned goods relief (RGR) is a customs relief that removes import duty, and in many cases import VAT, on goods that were exported earlier and come back. The goods must have been in free circulation when exported, return unaltered within three years and be supported by evidence of the original export.
How long do I have to return goods to claim RGR?
The standard limit is three years from the date of export. HMRC allows six years for Crown servants returning from overseas postings, and the three-year limit can be waived in listed cases, such as specialised equipment on long-term hire abroad or goods delayed by circumstances beyond your control. Waiver requests go to the National Import Reliefs Unit.
Is there a returned goods relief form?
There is no single RGR application form for most commercial imports, because you claim the relief in the import declaration itself. HMRC may ask you to complete forms C1314 and C&E 1158 in some cases. Duplicate lists, used for certain temporarily exported goods, are covered by form C&E 1246.
Does returned goods relief cover VAT?
It can. For VAT relief on a UK re-import, HMRC requires the exporter on the original export declaration and the importer on the re-import declaration to be the same person. In CDS, additional procedure code F05 relieves duty and VAT, while F01 relieves duty only. HMRC's CDS notes add that revenue reclaimed at export must be repaid on import.
Can I claim RGR if the goods were repaired or sold abroad?
Not normally. HMRC says the goods must not have been exported for repair or processing, and they must be unaltered apart from maintenance. VAT relief cannot be claimed if the goods were sold while outside the territory, unless specific conditions in HMRC guidance are met. For repaired goods, see our separate guide on returned goods after repair.
How do I claim RGR on goods returning to the UK from the EU?
Declare the goods to free circulation in CDS using procedure code 6110 with additional procedure code F01 or F05, and quote the original export MRN as a previous document in data element 2/1. If you have no export declaration, HMRC may accept alternative evidence that clearly identifies the goods and confirms their physical export and duty status.
Does returned goods relief apply in the EU and Ireland?
Yes. Article 203 of the Union Customs Code gives relief from import duty to goods that were exported as Union goods and return to the EU within three years in the state in which they left. GOV.UK points EU-bound traders to the national guidance of each member state, so check the rules of the member state where the goods arrive, including Ireland.
What if I am sending back goods I imported, rather than re-importing my own exports?
That is a different claim. HMRC can repay or remit charges on rejected imports that are defective, damaged before clearance or do not meet the contract. The time limit is one year, and you claim in CDS if you have an EORI number and the declaration was made in CDS, or through form C&E1179 in other cases.
Official sources
- GOV.UK: Pay less import duty and VAT when re-importing goods to the UK — HMRC
- GOV.UK: EU Returned Goods Relief
- GOV.UK: CDS requested procedure 61, re-importation with simultaneous release to free circulation — HMRC
- GOV.UK: CDS additional procedure codes, F-series — HMRC
- GOV.UK: VAT on goods exported from the UK (VAT Notice 703) — HMRC
- GOV.UK: Claim a repayment or remission of charges on rejected imports — HMRC
- GOV.UK: Making an entry summary declaration — HMRC
- GOV.UK: Get a goods movement reference — HMRC
- EUR-Lex: Regulation (EU) No 952/2013, Union Customs Code (Article 203)
Need help with a returning shipment?
Tell us what was exported, when and by whom, and we will check whether RGR applies. For fees, see the price list.
Disclaimer: The information on the site is operational and informational in nature and does not constitute legal or tax advice.
Do you need support with this procedure?
Contact our operations team. We respond 24/7.