ToR1 step by step — moving personal belongings to Great Britain
Moving your normal residence to Great Britain may allow eligible personal belongings to qualify for Transfer of Residence (ToR) relief from customs duty and import VAT. This guide explains the ordinary eligibility checks, evidence, ToR1 application and customs declaration steps, with separate conditions for other routes. Apply before shipping wherever possible; approval and eligibility depend on your circumstances.
Published
2026-06-10
Updated
2026-10-16
What is ToR relief and what charges does it actually waive?
ToR relief can cover customs duty and import VAT on eligible personal property when the applicable conditions are met. This guide concerns moves to Great Britain (England, Scotland and Wales). HMRC also provides ToR arrangements for moves to Northern Ireland from outside the EU; check the applicable NI rules. ToR relief is not needed for a move from the EU to Northern Ireland. This is not a complete NI declaration guide.
Apply for ToR approval before shipping wherever possible and use the approval reference in the applicable customs declaration. If the goods have already arrived, HMRC guidance allows a later application and, where approved, a claim for repayment of eligible charges; follow the procedure for the way the goods were declared. Prior approval remains a condition of the standard route in section 1 of the Reliefs reference document. Later applications must follow the specific HMRC procedure; approval and repayment are not automatic.
Who qualifies — the ToR conditions (12 months and 6 months)
The following ordinary Reliefs section 1 checks are not a universal test for every statutory route. Other bases can have different conditions and reference dates. Check which set of rules applies to your circumstances; do not combine conditions from different sets of rules.
Residence condition — 12 consecutive months outside the UK
For the standard Reliefs section 1 case, you must normally have been resident outside the UK for at least 12 consecutive months before establishing normal residence in the UK. HMRC may require evidence of that period.
Possession and use — the ordinary six-month condition
Non-consumables must have been possessed and used for at least six months before you ceased normal residence abroad; consumables must have been possessed for that period. Their intended UK use must match their use or intended use abroad. HMRC-approved exceptions and other statutory routes may have different tests. Check the relevant legal conditions rather than relying only on when the goods were shipped, whether you owned them or the date you describe as your moving date.
Exceptions — marriage, civil partnership, and students
Separate relief arrangements apply to qualifying full-time students and to qualifying marriage or civil-partnership imports. These routes have their own conditions and declaration requirements; check the relevant HMRC guidance rather than applying the ordinary ToR1 rules automatically.
What is covered and what is excluded
Check which goods satisfy the applicable personal-property conditions. Identify commercial or otherwise ineligible goods separately and confirm the appropriate declaration and any charges or other relief available.
Items covered by the relief
Subject to the applicable conditions, personal property may include household effects, private vehicles and trailers, campervans, leisure craft, private aircraft, pets and household provisions for normal family requirements. Any professional instruments must fall within the permitted category; portability alone does not make all business equipment eligible. Tax relief does not remove restrictions, licences or animal and vehicle requirements.
Exclusions — alcohol, tobacco, and more
The ordinary relief excludes alcoholic beverages, tobacco and tobacco products, commercial means of transport, and non-portable professional equipment. Check the precise permitted category for professional instruments. Goods outside this relief must be assessed under the appropriate declaration rules; do not assume that this excludes every other possible relief or allowance.
The ToR1 application — step by step
The normal preparation is to gather evidence, apply to HMRC and, once approved, use the ToR reference in the applicable customs declaration. If goods have already arrived, check the later-application and possible repayment procedure for the declaration used; do not assume automatic approval or repayment.
Step 1 — gather your documents and evidence
Prepare an inventory (similar items can be grouped with approximate counts), your passport photo page or the permitted military alternative, proof of your UK address dated within the past three months and proof of your usual non-UK address dated within the past six months. These are evidence-recency windows, not eligibility periods. If you do not yet have a UK address, HMRC permits alternatives such as evidence of temporary accommodation or a statement and address proof from your host. Supply animal documents as required for the route and application. For a vehicle, include its identifying details, registration number, purchase date, and the date and country of issue of the identification or registration document. HMRC may request further evidence; do not upload individual photographs of every belonging.
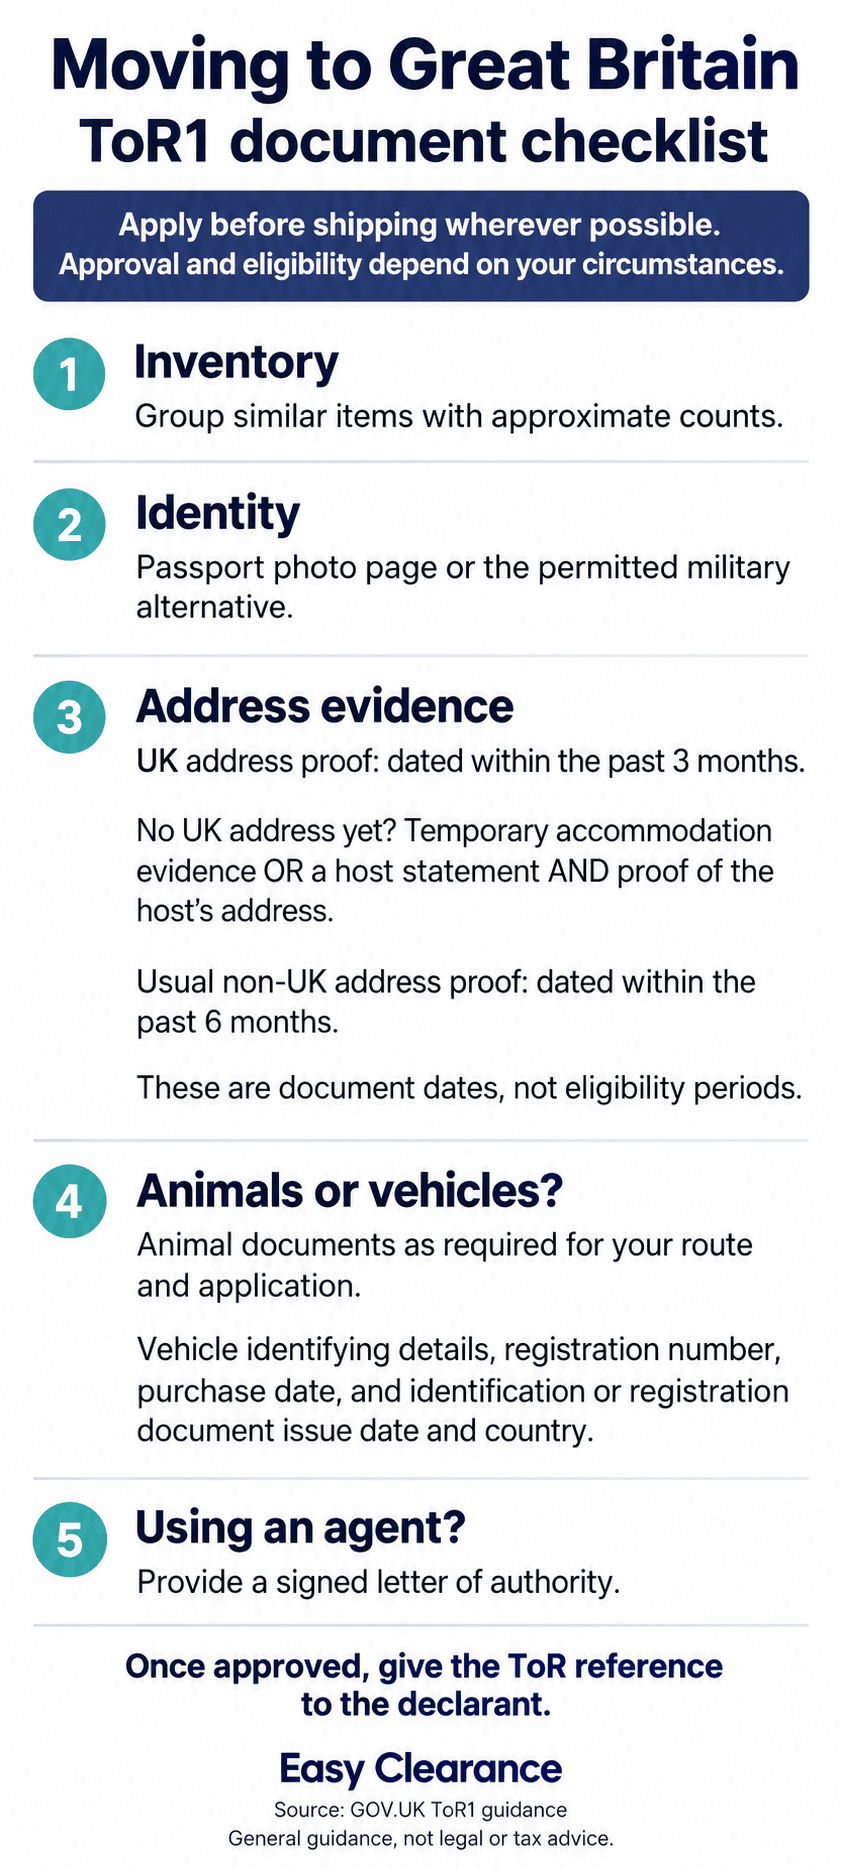
Moving to Great Britain
ToR1 document checklist
Apply before shipping wherever possible.
Approval and eligibility depend on your circumstances.
Inventory
Group similar items with approximate counts.
Identity
Passport photo page or the permitted military alternative.
Address evidence
UK address proof: dated within the past 3 months.
No UK address yet? Temporary accommodation evidence OR a host statement AND proof of the host’s address.
Usual non-UK address proof: dated within the past 6 months.
These are document dates, not eligibility periods.
Animals or vehicles?
Animal documents as required for your route and application.
Vehicle identifying details, registration number, purchase date, and identification or registration document issue date and country.
Using an agent?
Provide a signed letter of authority.
Once approved, give the ToR reference to the declarant.
Easy Clearance
General guidance, not legal or tax advice.
Step 2 — submit the online application to HMRC (or via an agent)
Sign in to HMRC's online ToR service, creating sign-in details if needed. You may apply yourself or use a representative with a letter of authority signed by you as the client. Do not assume that a particular sign-in provider is mandatory unless the service confirms it.
Step 3 — use the ToR reference number in the customs declaration
Once approved, provide the ToR reference to the declarant. For an eligible standard CDS declaration, use the appropriate procedure and C01 additional procedure code for customs duty relief; claim eligible import VAT relief with F45 as well. Confirm all codes and eligibility for the actual declaration. HMRC approval may allow eligible personal effects to be grouped under the relevant current Chapter 99 commodity code. Excise goods and prohibited or restricted goods are excluded from that simplification; verify the correct treatment of any vehicle and any separately classified goods. A practical guide to finding commodity-code information is in our Knowledge Base.
Common mistakes with ToR1 — and how to avoid them
Check these five points before preparing the application and shipment.
Mistake 1 — weak evidence of 12 months' residence outside the UK
Simply stating "I lived abroad for several years" is not enough. HMRC relies on documents: tenancy agreements, utility bills, bank statements showing a foreign address from the past 6 months, and proof of a UK address from the past 3 months. If for part of the period you stayed with family under no formal tenancy, start gathering alternative evidence well in advance.
Mistake 2 — failing to establish each item’s eligibility
Check and document the actual personal use, possession history and eligibility of each item. Packaging or multiple identical units may prompt questions, but do not by themselves prove commercial purpose or ineligibility for relief. Identify commercial or otherwise ineligible goods separately and confirm the appropriate declaration and any charges or other relief available.
Mistake 3 — selling or lending items within 12 months
Under the standard Reliefs conditions, do not lend, pledge, hire out or transfer relieved goods, free or for payment, within 12 months of import without HMRC approval. Confirm any different restriction period attached to your particular relief.
Mistake 4 — importing belongings after the 12-month deadline
In the standard case, declare the goods for free circulation within 12 months of establishing normal residence in the UK, not within 12 months of the approval date. Multiple consignments are possible; seek HMRC's decision before relying on early-import arrangements or an exception. Early-import and occupational-gap arrangements have additional conditions; confirm any undertaking, guarantee and applicable time limits before relying on them.
Mistake 5 — treating a vehicle as just another household item
For a permanently imported road vehicle, check HMRC's current notification route promptly: the usual deadline is 14 days, but who submits NOVA and the steps required depend on how the vehicle arrives and the importer. Complete any required NOVA processing, vehicle approval and DVLA registration; inspection is required only where applicable. These road-vehicle instructions must not be applied automatically to leisure craft or other categories of belongings. See the current HMRC vehicle-notification instructions.
Vehicle under ToR — what happens after clearance
An eligible private vehicle may be included in the application. Provide its identifying details, including the date and country of issue of its identification or registration document, and confirm its customs classification and all applicable declaration codes. For a permanently imported road vehicle, check HMRC's current notification route promptly: the usual deadline is 14 days, but who submits NOVA and the steps required depend on how the vehicle arrives and the importer. Complete any required NOVA processing, vehicle approval and DVLA registration; inspection is required only where applicable. These road-vehicle instructions must not be applied automatically to leisure craft or other categories of belongings.
Summary
For an eligible move to Great Britain, ToR relief can reduce customs duty and import VAT subject to the applicable statutory basis and HMRC decision. Check normal residence, possession and use, the permitted purpose, declaration deadline and post-import restrictions for your particular relief. Apply in advance wherever possible; later claims require the appropriate procedure and are not guaranteed. Use the approved reference and correct declaration codes, including F45 where eligible import VAT relief is claimed. Verify the current Chapter 99 treatment rather than assuming a fixed code or blanket vehicle exclusion. Separate rules apply to qualifying students and marriage or civil-partnership imports, while vehicles and animals may require additional formalities.
FAQ — frequently asked questions
How long do I need to have lived outside the UK to qualify for ToR relief?For the standard Reliefs section 1 case, you must normally have been resident outside the UK for at least 12 consecutive months before establishing normal residence in the UK. Non-consumables must have been possessed and used for at least six months before you ceased normal residence abroad; consumables must have been possessed for that period. Their intended UK use must match their use or intended use abroad. HMRC-approved exceptions and other statutory routes can have different conditions and reference dates. Separate relief arrangements apply to qualifying full-time students and to qualifying marriage or civil-partnership imports. These routes have their own conditions and declaration requirements; check the relevant HMRC guidance rather than applying the ordinary ToR1 rules automatically.
What is excluded from ToR relief?Ordinary relief excludes alcohol, tobacco and tobacco products, commercial means of transport, and non-portable professional equipment. Personal-property categories remain subject to eligibility; household provisions must meet normal family requirements and portability alone does not qualify all business instruments. Separate restrictions, licences and animal or vehicle requirements still apply.
How long do I have to bring my belongings to the UK after ToR is granted?In the standard case, declare the goods for free circulation within 12 months of establishing normal residence in the UK, not within 12 months of the approval date. Multiple consignments are possible; seek HMRC's decision before relying on early-import arrangements or an exception. Under the standard Reliefs conditions, do not lend, pledge, hire out or transfer relieved goods, free or for payment, within 12 months of import without HMRC approval. Confirm any different restriction period attached to your particular relief.
How do I apply for ToR1 and which code should I use in the customs declaration?Apply through HMRC's online ToR service, creating sign-in details if needed; an agent needs your signed authority. Apply for ToR approval before shipping wherever possible and use the approval reference in the applicable customs declaration. If the goods have already arrived, HMRC guidance allows a later application and, where approved, a claim for repayment of eligible charges; follow the procedure for the way the goods were declared. Prior approval remains a condition of the standard Reliefs route. Later applications must follow the specific HMRC procedure; approval and repayment are not automatic. For an eligible standard CDS declaration, use the appropriate procedure and C01 additional procedure code for customs duty relief; claim eligible import VAT relief with F45 as well. Confirm all codes and eligibility for the actual declaration. HMRC approval may allow eligible personal effects to be grouped under the relevant current Chapter 99 commodity code. Excise goods and prohibited or restricted goods are excluded from that simplification; verify the correct treatment of any vehicle and any separately classified goods.
Can I bring my car to the UK under ToR?An eligible private road vehicle may qualify for relief, subject to the applicable conditions. For a permanently imported road vehicle, check HMRC's current notification route promptly: the usual deadline is 14 days, but who submits NOVA and the steps required depend on how the vehicle arrives and the importer. Complete any required NOVA processing, vehicle approval and DVLA registration; inspection is required only where applicable. These road-vehicle instructions must not be applied automatically to leisure craft or other categories of belongings.
Official sources
- Transfer of residence to the UK — conditions, scope and exclusions — GOV.UK
- Application for transfer of residence relief (ToR1) — how to apply — GOV.UK
- Commodity codes when claiming transfer of residence relief — GOV.UK
- Bringing goods into the UK for personal use — GOV.UK
- Reliefs reference documents — standard transfer-of-residence conditions
- SI 1992/3193, article 11 — separate statutory conditions
- SI 1992/3193, article 7 — restrictions under that basis
- Georgiou v HMRC [2024] UKFTT 152 (TC) — overlapping statutory bases
- CDS additional procedure code C01 — duty relief and eligible VAT code F45
- HMRC notification routes for permanently imported vehicles
Pricing information: see our pricing page for current Easy Clearance rates for handling a ToR application and household effects clearance. An exact quote is provided once documents have been submitted.
Disclaimer: The information on this page is for general guidance only and does not constitute legal or tax advice. Material and language reviews completed on 16 October 2026.
Related articles
Moving to Great Britain? Ask Easy Clearance for help with your ToR1 application and customs clearance.
Get in touch to discuss your move and the assistance you need.