C79 certificate: what it is, how to download it and check your import VAT claim
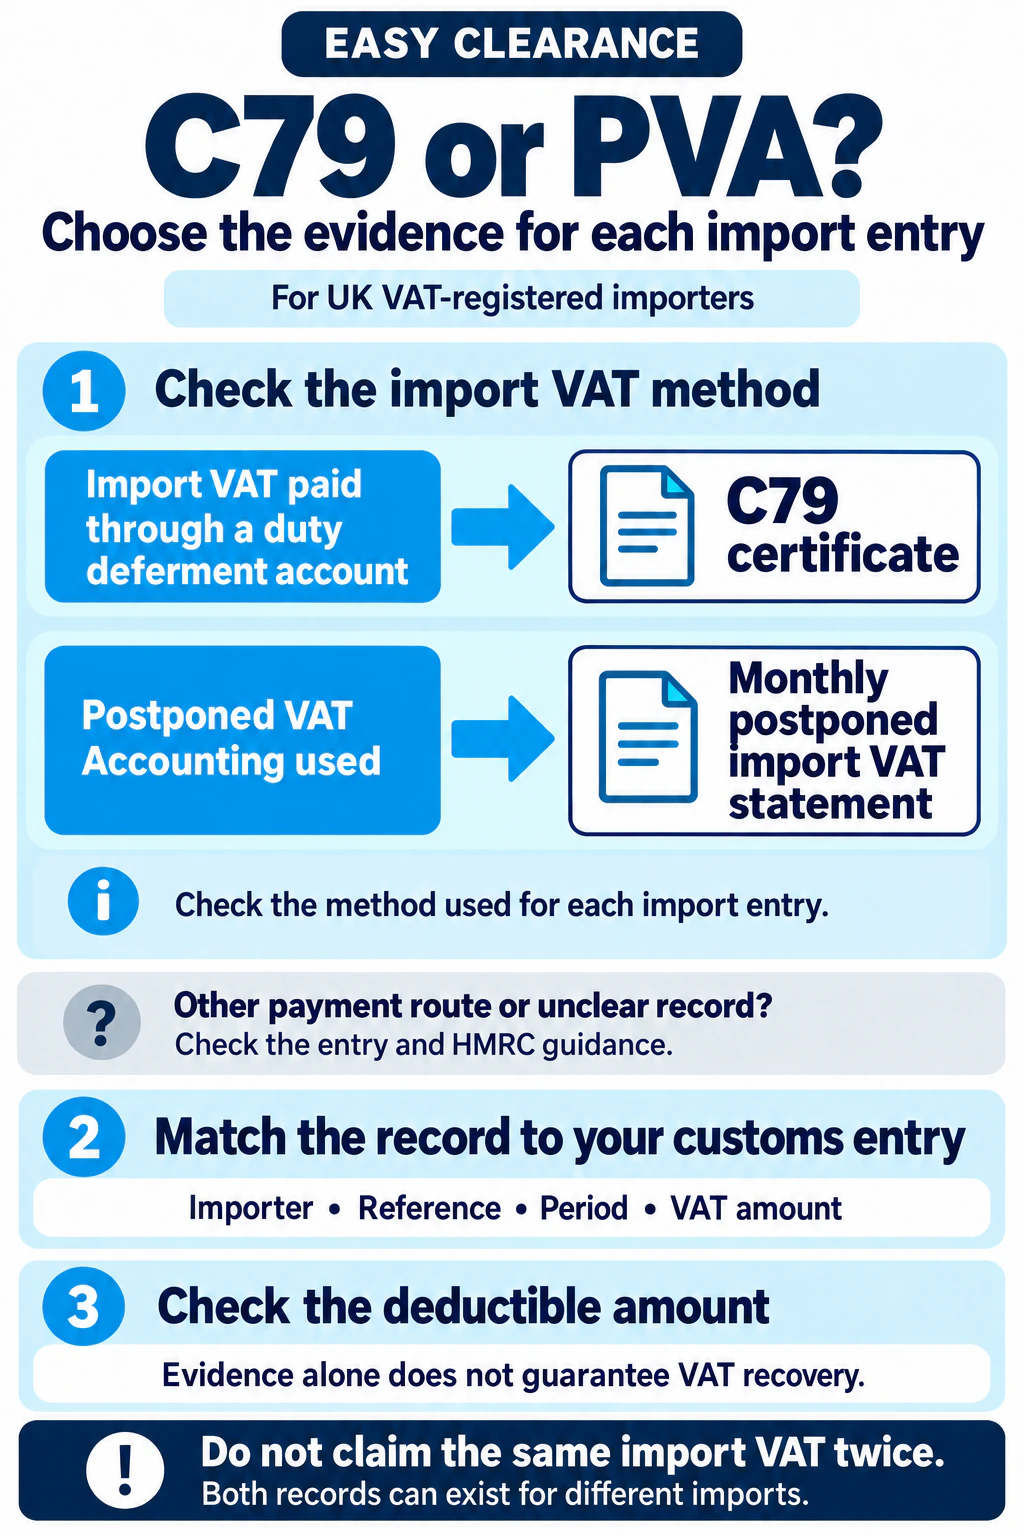
Your shipment has cleared customs, but your accounts team still needs the VAT evidence. Start with the declaration: was import VAT paid, or was postponed VAT accounting (PVA) selected? That determines whether you should look for a C79 certificate or a monthly postponed import VAT statement. Neither document, by itself, guarantees a right to reclaim VAT. HMRC: paying import VAT, HMRC: recipient of the supply.
What is a C79 certificate?
A C79 records import VAT paid and supports the evidence for an input tax claim. HMRC's current online C79 guidance covers import VAT paid using a duty deferment account. Paying a customs broker's invoice is not a substitute for checking the import VAT evidence and your entitlement. Keep the declaration, commercial documents and payment records together. Get your C79, HMRC: alternative evidence.
Download your certificate from HMRC
- Open the official C79 service and sign in using the details linked to the relevant EORI.
- Choose the month in which import VAT was paid. Certificates usually become available by the tenth working day of the following month.
- Download and retain a copy. Online access lasts six months from publication; older documents are archived, with access instructions in the Customs Declaration Service dashboard.
- Reconcile the certificate with the relevant import declarations before passing the records to the person preparing your VAT return. HMRC: C79 access, HMRC: check both sets of statements.
C79 or a postponed import VAT statement?
| Check | VAT paid on import | Postponed VAT accounting |
|---|---|---|
| Evidence | C79 where applicable to the payment route | Monthly postponed import VAT statement |
| Accounting | Eligible paid import VAT may be reclaimed as input tax | Import VAT is accounted for through the VAT return |
| Main safeguard | Check payment, importer identity and entitlement | Check the declaration's PVA selection and reconcile the statement |
A business can use different arrangements for different imports, so it may need both kinds of document during a month. Match each entry to its actual treatment and avoid claiming the same import VAT twice. A statement mismatch needs investigation; it does not justify automatically adding both amounts to a reclaim. HMRC: PVA eligibility and reconciliation, HMRC: VAT return treatment.
Check that the business can reclaim the VAT
UK VAT registration and a C79 are only part of the check. HMRC's policy generally links import VAT recovery to the owner of the goods. Business use, the relevant supply and normal input tax rules still matter. An overseas company should verify its UK VAT position and the import arrangements rather than assume that the certificate alone permits recovery. A freight agent acting for the importer does not automatically gain the importer's entitlement. HMRC: ownership and input tax.
How does this affect the VAT return?
Eligible import VAT already paid is normally included in the input tax claim in Box 4, with the purchase value included in Box 7 as appropriate. PVA has a different accounting trail: postponed import VAT is included in Box 1, the deductible amount in Box 4, and the import value excluding VAT in Box 7. The amount recoverable may differ from the amount due where normal deduction restrictions apply. Ask the person preparing the return to reconcile the documents to the correct accounting period. HMRC: paying import VAT, HMRC: completing the return.
Missing your C79? Check how import VAT was accounted for
Start by checking how import VAT was handled on the declaration. HMRC's C79 service covers import VAT paid using a duty deferment account. If you used postponed VAT accounting instead, look for your postponed import VAT statement.
For C79 records, check the declaration period and use the HMRC sign-in linked to your EORI. Download the relevant certificate and keep it with your import records. If you cannot identify which record you need, ask the declarant to confirm how import VAT was accounted for.
A C79 helps support a VAT reclaim; the treatment on your VAT return still needs to be checked for your circumstances. Discuss this with the person responsible for your VAT return.
Discuss your import VAT records
Contact Easy Clearance on WhatsApp — +44 7404 091503.
If the record is still unavailable
First check the payment route, the document month and the publication date. If PVA was used, look for the postponed statement instead. Check that you are using the correct business access and that the importer, EORI and VAT details on the declaration are correct. Ask the declarant for the entry reference and a copy of the declaration so you can trace the transaction. A representative's EORI may legitimately appear in the representative field: the issue is whether the importer and tax details were correctly entered, not whether a broker's EORI appears anywhere on the document. HMRC: CDS party identification fields. HMRC CDS party identification fields
If the appropriate statement remains unavailable, follow HMRC's service guidance and contact the imports and exports helpline where required. For PVA imports within a VAT group, the importing member accesses its own statement and passes it to the representative member for the group return. HMRC: C79 access, HMRC: postponed statements and VAT groups, HMRC: imports guidance.
Can you reclaim import VAT without a C79?
Do not treat a courier invoice as an automatic replacement. HMRC can consider alternative evidence where a C79 is missing, including evidence of ownership and import VAT charged. Acceptance is discretionary and depends on the circumstances and evidence requested. Keep your attempts to obtain the certificate and supporting transaction records; ask HMRC or your VAT adviser how to handle the claim. Missing evidence does not automatically mean permanent loss of recovery, and alternative evidence is not a routine shortcut. HMRC: alternative evidence for input tax.
Tell the customs broker how to account for VAT
PVA does not require separate HMRC approval, although the business and import must meet the conditions. If another person imports on your behalf and you want PVA, give written instructions before the declaration is made. Supply the correct EORI and VAT details, and keep the instructions. Customs duty deferment and PVA are different arrangements; choosing one does not establish that the other was used. HMRC: choosing PVA.
Do not assume that excise goods are excluded from PVA: HMRC permits it when relevant excise goods are released for home consumption, including release from an excise warehouse after duty suspension. Special procedures and postal imports have their own conditions, so verify the actual route. Great Britain and Northern Ireland also have different territorial rules. HMRC: PVA conditions.
Keep the records
VAT records generally need to be retained for at least six years, subject to the applicable exceptions and longer requirements. HMRC's records guidance says to keep C79 certificates in their original form. Downloading the certificate prevents its six-month online window becoming a records problem. Keep a clear link between the certificate, customs entry and accounting record. HMRC: record keeping, VAT Notice 700/21.
Frequently asked questions
Is the C79 the same as a PVA statement? No. They support different accounting treatments; check the declaration and payment route.
Does a C79 guarantee that I can reclaim all the VAT? No. The evidence and the entitlement must both be correct, and normal input tax rules apply.
Do I have to register separately for PVA? HMRC says separate approval is not required. Eligibility, correct declaration details and written instructions to your representative still matter.
Can a VAT-registered business outside the UK use PVA? It may be able to if the conditions are met. HMRC requires a non-established taxable person to have someone deal with customs and complete the declaration. UK VAT registration alone does not settle every recovery question. HMRC: PVA conditions.
Need help tracing the customs entry?
Send Easy Clearance the import route, declaration reference and the document problem you are trying to resolve. We can review the customs information and explain which records need checking. Confirm the final VAT return treatment with the person responsible for your tax affairs. Contact Easy Clearance.
Official guidance checked on 17 October 2026. This guide explains the process; your claim depends on the facts of the import and the applicable VAT rules.