T1 transit and import clearance: what happens at destination?
A delivery, a border crossing and an import declaration do not all mean the same thing as transit discharge. Plan what happens when the goods reach the transit destination, who presents them and how the next customs procedure will be handled.
Before the vehicle arrives
Confirm the transit office of destination or authorised consignee location, the movement reference and the time limit set for the movement. Make sure the carrier and recipient know that the goods are under transit and understand the presentation arrangements.
The location on the commercial delivery order may not be the place where the transit formalities are completed. An agreed unloading slot is not evidence that customs has accepted arrival or discharged the movement.
Arrival and presentation
The relevant goods and required information must be presented at the proper destination under the applicable procedure. For electronic destination handling, the arrival notification is made when the goods are at the required location. Customs validation and any control decisions follow.
The holder's obligations and the duties of carriers or recipients who know the goods are moving under transit must be addressed. Do not assume that a transport proof of delivery, invoice or port event completes those customs duties.
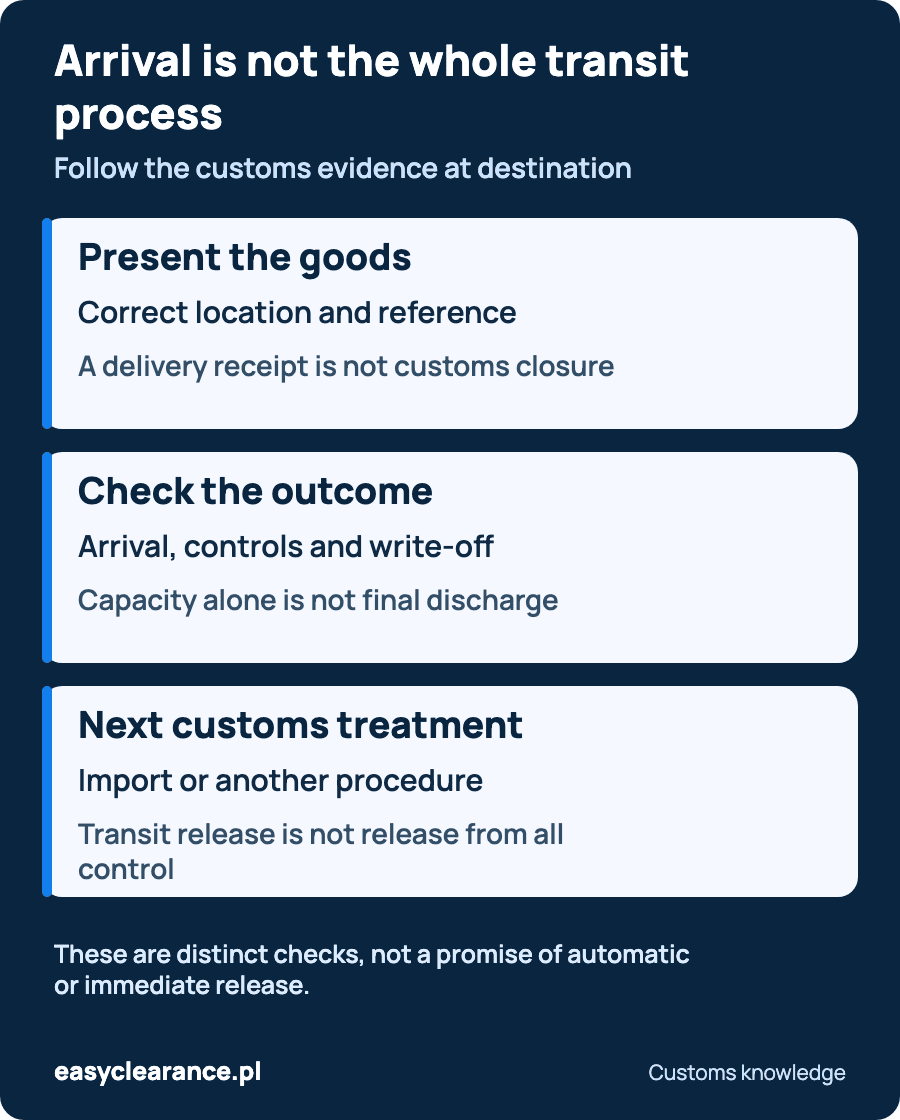
Ending and discharge are not just transport events
The legal and NCTS steps distinguish the end of a movement from its discharge or write-off following the required checks and comparison of information. Track the relevant customs status and evidence, including any discrepancies, instead of treating physical departure from Great Britain as automatic closure.
HMRC's detailed destination guidance also distinguishes guarantee-capacity handling from write-off. An arrival-related notification can affect capacity for specified guarantee types without proving that all transit obligations have ended. The applicable type and message sequence must be checked.
Plan the next customs treatment
Release from the transit procedure is not a general release from customs control. Goods may need release for free circulation or entry into another appropriate procedure. The declaration and conditions for that next treatment are a separate part of the plan.
For customs warehousing, do not confuse ending transit with entering or later removing goods from the warehouse procedure. HMRC also recognises entry-to-warehouse movement covered by the import declaration entering warehousing, so transit is not a compulsory extra label for every warehouse delivery.
A CDS import declaration on its own should not be treated as automatic proof of NCTS write-off. Where arrival was missed or a movement is not discharged, use the applicable enquiry and evidence process rather than assuming that a later import entry has resolved everything.
Keep status and direction clear
The route does not remove the need to establish customs status. HMRC describes GB domestic goods exported under transit as T1, while qualifying Union goods moving EU–GB–EU may retain T2 status. The appropriate destination and subsequent formalities must be planned for that actual status and movement.
This article concentrates on destination control and follow-up. For the earlier route and guarantee decision, use the separate planning guide linked below rather than choosing T1 solely because a vehicle travels through Great Britain.
A destination follow-up checklist
If a movement remains open, contact the holder or the responsible customs representative promptly with the movement details and available evidence. This guide does not promise automatic closure, release or a standard refund deadline.
- Confirm the correct movement reference, office or authorised location and presentation time limit.
- Record actual presentation and the customs arrival or control evidence.
- Resolve any discrepancies and follow the applicable instructions before unloading or removing goods.
- Check the relevant discharge or write-off evidence; do not substitute a commercial delivery event.
- Confirm the next customs treatment and who retains the supporting records.
- Check guarantee-capacity information and any commercial security separately from the movement's final status.
Frequently asked questions
Does leaving Great Britain by ferry discharge transit?
Not as a general rule. Physical departure is not a substitute for the required destination presentation, checks and discharge or write-off process for the actual transit movement. Track the relevant customs evidence.
Does an import declaration automatically close NCTS?
Do not assume so. HMRC's guidance on missed presentation warns that a CDS entry alone is not accepted alternative evidence for transit write-off. Follow the applicable presentation or enquiry process and verify the movement's status.
Does warehouse arrival mean customs control has ended?
No. Transit ending or discharge, entry into customs warehousing and later discharge from warehousing are different matters. The goods need the appropriate customs treatment and evidence, not just a commercial proof of delivery.
Is restored guarantee capacity proof of final discharge?
Not by itself. HMRC describes arrival-related capacity restoration for specified guarantee types separately from write-off. Check the relevant movement status and guarantee evidence rather than using available capacity as the only proof.
Official sources and guidance
Sources checked for this revision on 17 October 2026. HMRC completion instructions and guidance are distinguished from legislation; check the current instructions for the specific movement.
Discuss the actual movement
Send the route, goods description and intended customs treatment so the relevant document checks can be identified.
WhatsApp: +44 7404 091503Contact Easy Clearance