Dropshipping to the UK 2026 – Who Pays Customs Duty and VAT?
A guide for Polish businesses dropshipping to the UK: who is responsible for customs duty, how the £135 threshold works, what DDP and DAP terms mean and why marking parcels as "gifts" is illegal and prosecuted by HMRC.
smart_displayWatch the video guide
Dropshipping to the UK: who pays VAT and duty?
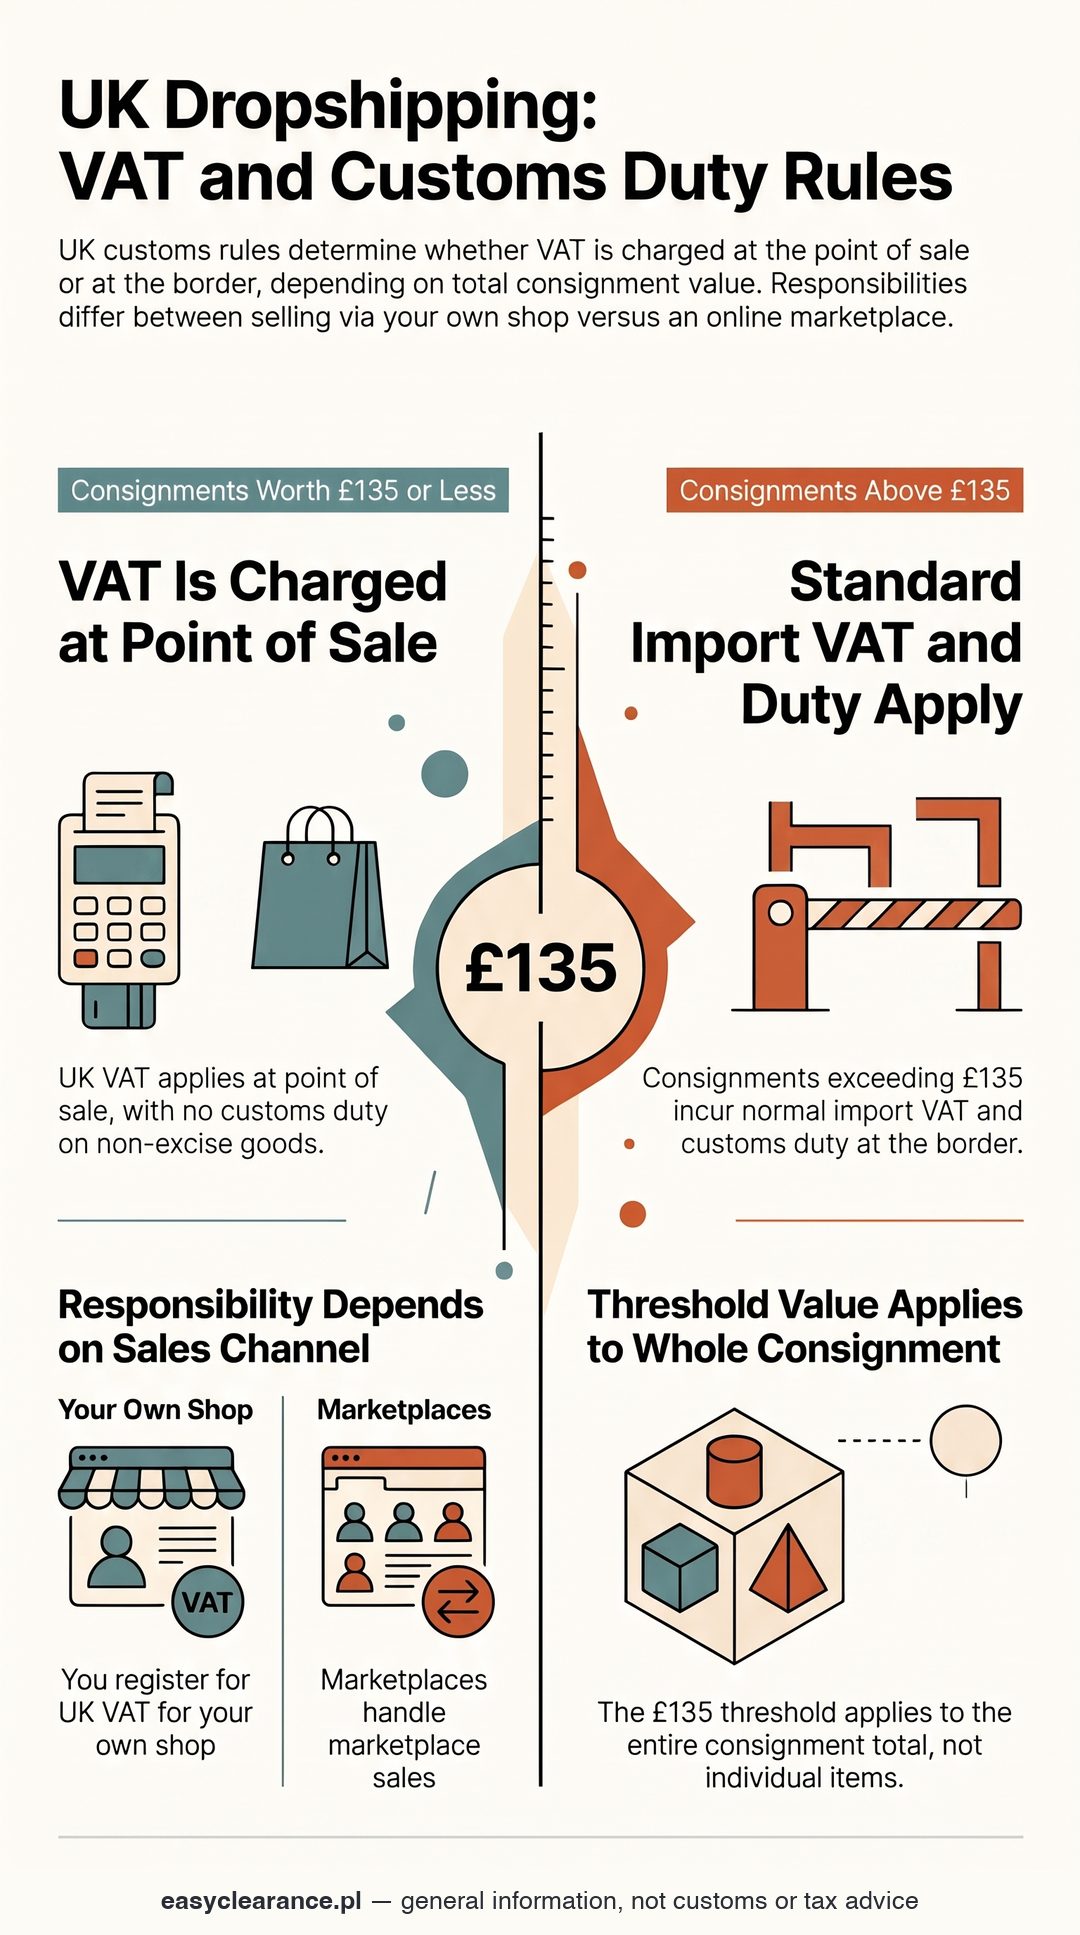
Dropshipping to customers in Great Britain? For consignments of 135 GBP or less, VAT is charged at the point of sale — by you on your own shop, or by the online marketplace. Above 135 GBP, normal import VAT and customs duty apply.
Watch on YouTubeAuthor
easyclearance.pl teamPublished
15 April 2026
Updated
21 October 2026
Quick answer
In dropshipping to the UK, liability for customs duty depends on the shipment value and delivery terms. Goods up to £135 — VAT is collected by the marketplace (Amazon, eBay). Goods above £135 — the importer is the buyer (DAP) or the seller (DDP). Dropshipping from China requires two customs clearances and may be subject to anti-dumping duties. Falsifying customs values or marking shipments as "gifts" is illegal and carries HMRC penalties.
Quick summary
After Brexit the UK abolished Low Value Consignment Relief. Every parcel entering the UK is subject to VAT. For shipments up to £135 VAT is accounted for by the marketplace or online seller (OMP). For shipments above £135 — the importer must handle customs clearance and VAT. A dropshipper must decide: DDP (bears costs themselves, customer receives parcel with no extra charges) or DAP (customer pays duty on delivery, which often causes returns). For dropshipping from China — HS code, rules of origin and potential anti-dumping duties also matter.
Planning dropshipping to the UK?
We help structure your customs model — DDP, DAP, UK VAT registration. Ask on WhatsApp.
Definition of dropshipping and the question of customs liability
Dropshipping is a sales model in which you do not hold goods in stock — you order from a supplier (in Poland, China, Turkey) only after receiving an order from an end customer, and the supplier ships directly to the buyer. The customs problem arises when your customer is in the UK and the goods come from outside the UK.
The question "who pays customs duty" in dropshipping has no single answer — it depends on three factors: shipment value, Incoterms (DDP vs DAP) and sales channel (marketplace or own shop). Below we explain each scenario.
The £135 threshold — goods below this value
Since 1 January 2021 HMRC abolished Low Value Consignment Relief (LVCR), which previously exempted small parcels from VAT. Now every commercial consignment entering the UK, regardless of value, is subject to VAT (the only exemption left is for genuine gifts between private individuals worth £39 or less).
For shipments with a value up to £135 (goods value excluding delivery costs and insurance):
- Import customs duty is not charged (Relief from customs duty)
- VAT (20%) is collected at the point of sale — by the marketplace (Amazon, eBay, Etsy) or by you as the online seller
- If you sell via Amazon.co.uk or eBay.co.uk — the marketplace collects VAT from the buyer and pays it to HMRC. You do not need to register for UK VAT solely on this basis.
- If you sell via your own shop (Shopify, WooCommerce) — you must register for UK VAT and charge 20% VAT on the invoice
In practice most dropshippers selling low-cost goods (electronics, gadgets, clothing) via Amazon or eBay may not need to register for UK VAT if they only sell consignments of £135 or less through a marketplace that accounts for the VAT. Note: for businesses not established in the UK there is no turnover threshold — the £90,000 registration threshold applies to UK-established businesses (HMRC VAT Registration Manual, VATREG37210).
How the £135 threshold is applied — whole consignment, excise goods, gifts
The £135 limit applies to the value of the whole consignment, not to a single item in the basket. The "VAT at the point of sale" rule also has exceptions:
- it does not cover consignments containing excise goods — normal import rules apply to them, and Customs Duty on excise goods (alcohol, tobacco, vaping liquid, pre-filled vapes) is payable whatever the value;
- it does not apply to non-commercial goods, such as gifts;
- a marketplace is liable for the VAT only if the goods are outside the UK at the point of sale, the consignment is not more than £135 and it contains no excise goods.
For consignments above £135, normal VAT and customs rules apply on importation into Great Britain (GOV.UK, VAT and overseas goods sold directly to customers in the UK).
Goods above £135 — importer of record: buyer or seller?
When the goods value exceeds £135, standard UK customs rules apply. The goods must be cleared through customs, import duty and import VAT must be paid. Who does this depends on the Incoterms:
DAP — Delivered At Place (buyer is the importer)
Under DAP terms (formerly DDU) the buyer is responsible for customs clearance and payment of duty and VAT on delivery. In practice couriers (DHL, FedEx, UPS) invoice the buyer for the duty and VAT, often with their own handling fee on top. Many UK buyers refuse to accept a parcel with an unexpected customs surcharge → high return rate, negative reviews, losses.
DDP — Delivered Duty Paid (seller is the importer)
Under DDP terms you as the seller pay customs duty and VAT, and the buyer receives the parcel "duty-free". This is better for the customer experience but requires you to hold a GB EORI number, a UK VAT number and knowledge of HS codes for your products.
At Easy Clearance we help dropshippers set up the DDP model — UK VAT registration, GB EORI and clearance handling for regular dropshipping deliveries.
Dropshipping from China: HS code, double clearance, rules of origin
Dropshipping from China to the UK is particularly complex. Goods shipped directly from China to the UK require:
- Correct HS code in 10-digit UK Trade Tariff format — must match the goods, otherwise HMRC penalties and investigations follow
- Import clearance in the UK — electronic declaration in the CDS system (data elements per UK Trade Tariff Volume 3 for CDS), customs value, country of origin (China), tariff rate
- Import VAT or marketplace settlement for parcels up to £135
A key issue is rules of origin. Goods manufactured in China have Chinese origin — they do not become "Polish" or "European" simply by being repacked. The UK tariff treats them as goods from China, with the corresponding tariff rate (often higher than for EU goods).
For goods shipped from Poland but manufactured in China (dropshipping via a European warehouse), the UK tariff rate depends on the actual country of manufacture, not the country of dispatch.
What "UK importer of record" means for non-UK businesses
A Polish company that imports goods into the UK as part of dropshipping can act as the UK importer of record — but must meet several conditions:
- Hold a GB EORI number (apply on GOV.UK; usually issued immediately, or up to 5 working days if HMRC needs to make checks)
- Be registered as a UK VAT payer (a business not established in the UK making supplies of goods in the UK — no turnover threshold; the £90,000 threshold applies to UK-established businesses)
Many dropshippers use the services of a UK freight forwarder or customs broker as an import intermediary (customs agent acting as indirect representative) — this is simpler than self-registration when sales are irregular.
Who is liable for the customs debt — direct and indirect representation
The customs debtor is the person who made the import declaration. If you hand clearance to a customs agent, liability depends on how the agent acts on the declaration (GOV.UK, Customs debt liability):
- Direct representation — the agent acts in your name. You, as the principal, are solely liable for the customs debt. The agent becomes jointly and severally liable only if you gave clear instructions and the agent made a deliberate or unreasonable error.
- Indirect representation — the agent acts in its own name on your behalf. The agent and the principal are then jointly and severally liable, and HMRC may seek payment from either of them.
- If the declaration does not state the type of representation, or the agent is not empowered to act as a representative, the agent is treated as acting in its own name and on its own behalf.
The instruction to your agent should be in writing and show whether they act directly or indirectly. According to GOV.UK, who is liable depends on the services provided and the commercial agreement, and you remain responsible for due diligence on your customs declarations.
The UK warehouse (3PL) model — the seller as importer
When goods first go to a warehouse or fulfilment centre in the UK and are shipped to customers from there, this is no longer classic "supplier to customer" dropshipping. Liability then looks different:
- An overseas seller who owns goods located in the UK at the point of sale (of any value) must register for VAT and account for it, unless all of its supplies are zero-rated (GOV.UK, VAT and overseas goods sold directly to customers in the UK).
- If the goods are sold through an online marketplace, the marketplace is liable for the VAT on the sale to the customer, but the seller remains liable for import VAT and Customs Duty when the goods are first imported into the UK. A registered seller can reclaim import VAT under the normal input tax rules (GOV.UK, VAT and overseas goods sold to customers in Great Britain using online marketplaces).
In this model the importer is therefore the seller (or its customs representative), and the type of representation should be decided before the first delivery. For the cost of clearance services, see the pricing page.
GB EORI — when required for a dropshipper
A GB EORI number is needed for customs declarations for goods moved into Great Britain — for example when you are the importer under DDP, bring stock into a UK warehouse or make your own customs declarations. If you sell exclusively via Amazon or eBay and every consignment is £135 or less, the marketplace accounts for the VAT at the point of sale; customs declarations are still made for the parcels, so confirm with your carrier or HMRC whether an EORI in your name is needed.
However, as your revenue grows or you move into premium segments (higher-value products), a GB EORI becomes essential. Registration is free on GOV.UK — the number is usually issued immediately, or within up to 5 working days if HMRC needs to make checks.
The trap: parcels sent as "gifts" — HMRC does not accept this
One of the most common abuses in dropshipping from China is marking goods that were sold as a "gift" with an understated value below £39. The VAT exemption up to £39 applies only to genuine gifts (non-commercial goods sent as a present) — goods sold to a customer are not a gift, and labelling them as one is an incorrect declaration. Commercial consignments are subject to VAT whatever their value.
HMRC regularly inspects courier and postal shipments from China. Consequences for a dropshipper:
- Seizure of goods by HMRC
- Payment of the VAT and duty due, plus financial penalties for an incorrect declaration
- Possible criminal proceedings for systematic falsification of values
The only legal option is to declare the correct goods value and pay the appropriate VAT via the marketplace or your own UK VAT registration. Read more about errors on customs invoices.
FAQ — frequently asked questions about dropshipping to the UK
As a dropshipper from Poland, do I need to register for UK VAT?
It depends on your model. If you sell via a marketplace (Amazon, eBay) and all orders are below £135 — the marketplace collects VAT on your behalf and you do not need to register. If you sell consignments of £135 or less directly to customers in Great Britain (e.g. via your own shop), you charge UK VAT at the point of sale and must register. For businesses not established in the UK there is no turnover threshold — the £90,000 registration threshold applies to UK-established businesses.
Who pays customs duty in DDP dropshipping from China?
Under DDP (Delivered Duty Paid) terms you as the seller pay import duty, VAT and all customs charges. The buyer receives the parcel with no surcharges — which is the standard for a good shopping experience in the UK market. This requires holding a GB EORI number and UK VAT, or working with a customs broker acting as your representative.
What should I do if a UK customer received a customs bill from the courier?
This means the shipment was on DAP terms and the buyer is the importer of record. You can cover that cost as compensation (bank transfer), offer a refund, or switch to a DDP model in future. Many complaints and negative reviews on Amazon / eBay result from unexpected customs charges on delivery.
Who is liable for the customs debt if I use a customs agent?
It depends on the type of representation. Under direct representation the principal is liable for the customs debt, and the agent only exceptionally, after clear instructions and a deliberate or unreasonable error. Under indirect representation the agent and the principal are jointly and severally liable, and HMRC may seek payment from either.
Current rules — as of 2026
The rules on dropshipping and VAT for UK shipments have been in force since 1 January 2021. HMRC is tightening controls on small parcels from China, implementing risk-based targeting at the border. The information in this article reflects the legal position as of April 2026.
Official sources
- GOV.UK: VAT and overseas goods sold to customers in the UK — HMRC, 2026
- GOV.UK: Customs duty on goods brought into the UK — HMRC, 2026
- GOV.UK: Customs debt liability — HMRC, 2026
- GOV.UK: Appoint someone to deal with customs on your behalf — HMRC, 2026
- GOV.UK: VAT and overseas goods sold to customers in Great Britain using online marketplaces — HMRC, 2026
- GOV.UK: Tax and duty on goods sent from abroad — HMRC, 2026
Disclaimer: The information on this page is operational and informational in nature and does not constitute legal or tax advice. Customs procedures and rates are subject to change — always verify current HMRC regulations and contact a customs broker before shipping.
See also
Ask about customs duty for your dropshipping
We help set up the DDP model, register UK VAT and optimise customs costs for your UK dropshipping. We respond on WhatsApp.